
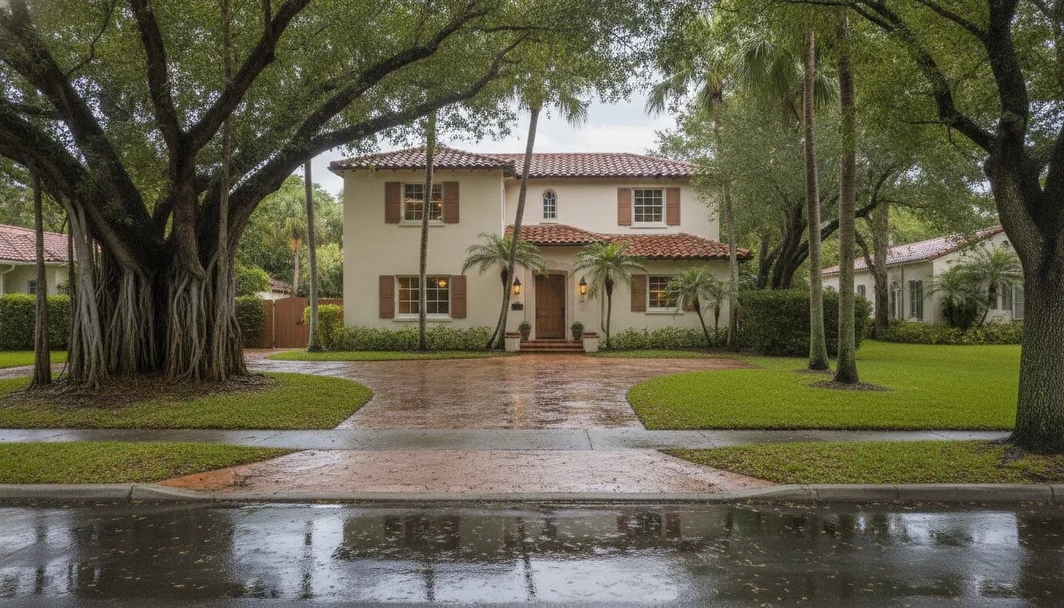
Coral Gables Flood Zone House: Buyer Checks
A coral gables flood zone house is not judged by the listing photos. The useful question is whether that address sits in a mapped flood hazard area. Also ask how high the first floor sits. Then ask what a lender and an insurer will require before you can close. Two houses on the same Coral Gables block can face different rules.
Ask The Maya Vander Group to review a Coral Gables house before you offer
Start with the official map, then the elevation certificate, then a written insurance quote. If the house is also locally designated historic, check whether a planned lift or addition needs a separate city review. This page stays on those checks. For a wider look at home types and daily life, use the Coral Gables luxury real estate guide.
What a Coral Gables Flood Zone House Means
Coral Gables sits near sea level, with groundwater close to the surface. The city is bordered by the Atlantic Ocean, Biscayne Bay, the Miami River, lakes, and canals. Heavy rain can pond in low streets because the water has little place to go. Storm surge is a separate risk during a hurricane.
The official map for this risk is the Flood Insurance Rate Map, or FIRM. FEMA draws Special Flood Hazard Areas on that map. Those areas are subject to the 1 percent annual-chance flood, sometimes called the 100-year flood. The City of Coral Gables says a structure in that area has, on average, about a 26 percent chance of flooding during a 30-year mortgage. That is a long-term odds statement, not a forecast for one storm season.
A house outside the shaded high-risk area is not automatically dry. The city's 2024 flood brochure notes that in 2020 more than 25 percent of claims paid by the National Flood Insurance Program came from outside the Special Flood Hazard Area. A "preferred" or moderate zone can still flood from a stalled rainstorm.
Miami-Dade County requires a full disclosure when improved property in a Special Flood Hazard Area or a Coastal High Hazard Area is sold. The disclosure tells the buyer the property lies in that zone. It does not tell you the premium, the height of the floor, or whether a future renovation will trigger a rebuild. Those are separate checks.
How to Confirm the Flood Zone for One Address
Do not rely on a neighborhood label or a prior listing. Confirm the parcel. Use more than one source, because a panel boundary or a map revision can change what a casual search shows.
- Open the current FIRM for the address on the FEMA Map Service Center and note the zone and the map panel.
- Cross-check the parcel on Miami-Dade's flood maps, which the city points buyers to for local viewing.
- Call the Miami-Dade Flood Zone Hotline at 305-372-6466 and ask for the designation on that property.
- If you want a written city determination, Coral Gables will make one for a property inside the city upon written request. The published fee is $152.25. The Building Official line listed on the city brochure is 305-460-5242.
- Ask whether a Letter of Map Amendment or Letter of Map Revision is already on file. Those letters can change how a structure is treated even when the printed panel looks unchanged.
Write down the zone code, the date of the map panel, and who confirmed it. A screenshot with no panel date is a weak record once you are in contract. If the result is unclear, pause the offer timeline until the county or the city confirms it in writing.
Zone names are easy to mix up. A zone starting with A or V is generally a Special Flood Hazard Area. V zones add wave action and usually mean stricter elevation and foundation rules. An X zone, shaded or unshaded, is outside that high-risk boundary, but the city still urges flood coverage there. Ask the hotline which side of the line the building sits on, not only the lot.
What to Read on the Elevation Certificate
An elevation certificate is a surveyed form. It records how high the house was built relative to the flood zone and the base flood elevation. Coral Gables requires one for new construction and for substantial improvements. It is also one of the clearest documents a buyer can use when an insurer prices the policy.
Miami-Dade's records are the practical starting point, with an important date limit. If the home was built after 1995, the county may already have the certificate in its elevation-certificate search. If that search is empty, call the Flood Zone Hotline. If the home was built before 1995 and has not been substantially improved or substantially damaged, the county says its records start in 1995. You may need a surveyor to produce a current certificate.
Read these fields before you treat the form as good news, and keep a copy with the contract so the numbers do not get separated from the offer.
- The building diagram and the height of the lowest floor, or the first floor, compared with the base flood elevation.
- Whether any enclosure below that floor is a garage, storage, or finished living space.
- The flood zone and the FIRM panel date printed on the form. An old panel date can disagree with the map you just pulled.
- The surveyor's date. A certificate from a prior renovation may not describe the house as it stands today.
A higher first floor can reduce the premium under current NFIP pricing. It does not erase the zone, and it does not replace an insurance quote. If the seller cannot produce a certificate, build the survey cost and the waiting time into the inspection period. Order it early. A survey booked after the inspection deadline helps the next buyer, not this contract.
How Flood Insurance Is Priced on a Coral Gables House
A standard homeowners policy does not cover flood damage. Coral Gables says this directly, and it is the mistake that surprises out-of-town buyers. Coral Gables participates in the National Flood Insurance Program. So federally backed coverage is available for structures in the city whether or not they sit in a Special Flood Hazard Area. Private flood policies may also be offered. Compare both. The requirement and the price are different questions.
If you use a federally regulated lender and the house is in a Special Flood Hazard Area, flood insurance is required. A cash purchase does not remove the risk. It only removes the lender's mandate. The city still recommends coverage outside the high-risk zones because rain and drainage flooding are not limited to the shaded map area.
Pricing no longer depends only on the zone printed on the map. FEMA's Risk Rating 2.0, fully implemented on April 1, 2023, sets NFIP premiums from property-specific factors. Those factors include flood frequency, the type of flooding, distance to water, the height of the first floor, and the cost to rebuild. Coral Gables lists the same building-level factors and notes that the renewal change began on April 1, 2022.
Do not expect a neighbor's premium to match yours. Two coral gables flood zone houses with the same bedroom count can price differently because the floor height and rebuild cost differ. The Congressional Research Service describes the statutory caps. A primary-residence NFIP premium generally cannot rise more than 18 percent in a year. Some other property categories can rise up to 25 percent a year until the full risk rate is reached. A cap limits the annual jump. It does not freeze the premium.
There is also a timing trap. A new flood policy generally does not take effect until 30 days after purchase. If you wait until the week of closing, you can be in the house with no flood coverage and. In a financed SFHA purchase, a lender that will not close. Ask for quotes during the inspection period, for both the building and the contents.
| Check | Where to confirm it | Why it changes the offer |
|---|---|---|
| Flood zone and map panel | FEMA Map Service Center. Miami-Dade flood maps. Flood Zone Hotline, 305-372-6466. | Shows whether disclosure and lender insurance apply. |
| Written city determination | Coral Gables Development Services. Published fee, $152.25. | Creates a city record when online panels disagree. |
| Elevation certificate | Miami-Dade search for many post-1995 homes. A surveyor if the file is missing. | Shows first-floor height, which drives pricing. |
| NFIP or private quote | An insurance agent, using zone, floor height, and rebuild cost. | Many new policies wait 30 days. The premium is property-specific. |
| Substantial-improvement plan | Coral Gables flood ordinance and the Florida Building Code. | A large renovation can force elevation work. |
| Historic status | City Historic Preservation. A Certificate of Appropriateness if designated. | Some exterior elevation work needs board review. |
When a Renovation Crosses the Substantial-Improvement Line
Buyers often plan a new kitchen, a roof, or a full interior the moment they close. In a flood hazard area, the size of that work can matter as much as the design. Coral Gables Chapter 113, the Flood Damage Prevention ordinance adopted in its current form under Ordinance No. 2021-18, applies to development in a flood hazard area. The scope includes alteration, enlargement, repair, and demolition, and it works together with the Florida Building Code.
The city also states that elevation certificates are required for substantial improvements, not only for brand-new houses. If the planned work crosses the local substantial-improvement test, the permit review can require the house to be brought into compliance with current flood-resistant construction. That can mean raising the finished floor or changing the foundation, not only swapping finishes.
Do not guess the percentage from a blog post. Ask Development Services how the current code measures the improvement against the structure's market value, and whether your scope is one project or a series of permits. Bring a contractor estimate to that conversation. A house that looks like a light remodel on a showing can become a floodplain compliance project once the numbers are on paper.
This is also why the elevation certificate belongs in the offer file. If you may improve the house, you want to know the starting elevation before you agree to a price that assumes a simple renovation.
How Historic Review Changes the Same House
Age and designation are not the same thing. Coral Gables has protected historic buildings since its first preservation ordinance in 1973. Local landmark or local historic-district listing is a formal status. The city's preservation guide says designation generally requires a property at least 50 years old that also meets adopted significance criteria. A 1920s house that was never designated does not automatically enter that process.
When a house is on the local register, exterior alterations are reviewed through a Certificate of Appropriateness. That review is separate from the flood permit. Raising a designated house, changing its porch, or altering the street facade can require Historic Preservation staff and, in many cases, the Historic Preservation Board. Staff plan-review hours are Mondays and Wednesdays, 9 a.m. to noon. The division can be reached at hist@coralgables.com.
Use historic review as a flood question, not as a style essay. Ask three things: is this address locally designated, does the elevation or renovation plan touch reviewed exterior features. And how long does that review usually take relative to your inspection and permit timeline. Interior paint is not the issue. A new finished-floor height often is.
If you are still deciding whether Coral Gables is the right city at all, the Coconut Grove and Coral Gables family comparison covers schools and daily life. Keep this flood file focused on the parcel you are underwriting.
What to Settle Before You Write the Offer
Treat flood diligence as a short sequence inside the inspection period. The goal is a premium and a permit answer you can live with, not a perfect prediction of the next storm.
- Confirm the zone in writing and save the map panel date.
- Obtain the elevation certificate or a surveyor proposal with a delivery date.
- Get at least one NFIP quote and, if available, one private quote that states the waiting period.
- Ask the lender, if you have one, whether the zone triggers a coverage minimum at closing.
- If you plan work in the first year, ask the city whether that scope is a substantial improvement.
- If the house is locally designated, ask Historic Preservation whether the elevation plan needs a Certificate of Appropriateness.
A missing certificate or a slow insurance quote is a contract problem, not a detail for the walkthrough. Extend the inspection period or adjust the price only after you have the document, not after a verbal "it should be fine."
Current listings change every day. Use the Coral Gables homes search to see what is on the market, then run this file on the one or two houses that fit. The Coral Gables homes-for-sale guide explains how to compare location and condition across those listings. It is the companion to this page, not a substitute for the map and the certificate.
Bring The Maya Vander Group the address you are considering
Frequently Asked Questions
Does every Coral Gables house sit in a flood zone?
No. FEMA maps show which parts of the city fall in a Special Flood Hazard Area and which sit outside it. You still need the designation for the specific building. The city warns that flooding also happens outside the high-risk shading, including from heavy rain.
Is flood insurance optional if I pay cash?
A lender requirement usually applies when a federally regulated mortgage covers a house in a Special Flood Hazard Area. Cash removes that mandate, not the exposure. Standard homeowners insurance still does not cover flood, and a new policy often has a 30-day wait.
Will an elevation certificate lower my premium?
It can, because Risk Rating 2.0 uses first-floor height, but only a quote from an insurer can say so. The certificate is the evidence. A higher floor relative to base flood elevation is generally treated more favorably than a floor below it. Confirm the figure against the current map before you rely on it.
Do I need historic approval to raise the house?
Only if the property is locally designated, or otherwise subject to Coral Gables historic review, and the work changes reviewed features. Many older houses are not designated. Ask Historic Preservation for the address before you assume a Certificate of Appropriateness is required.
Can I use a neighbor's flood premium as my budget?
No. Premiums depend on that structure's floor height, flood frequency, distance to water, and rebuild cost. Annual NFIP increases for a primary home are generally capped, but the cap is not the price. Get a quote on the house you intend to buy.
Ready to Explore Luxury Real Estate in Miami?
Don't miss opportunities in one of Florida's most desirable markets. Contact Maya Vander today for exclusive access and personalized service.


