
South of Fifth: A Miami Beach Buyer Guide
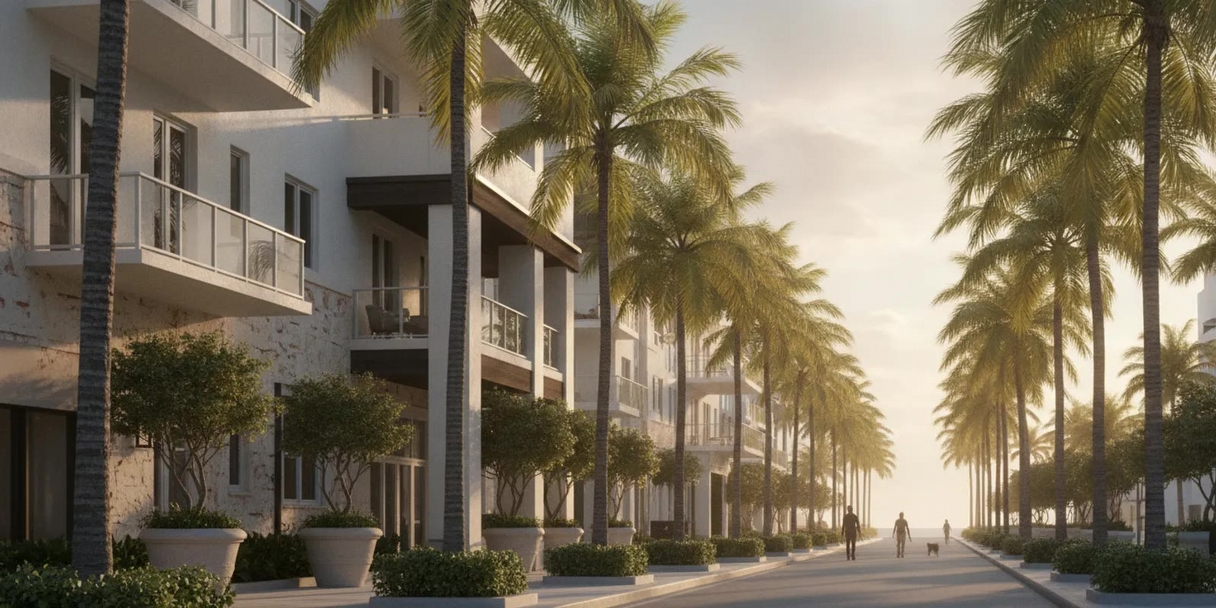
South of Fifth is the compact residential pocket at the southern tip of Miami Beach, south of Fifth Street. Buyers shorten the name to SoFi. It is a neighborhood, not one building and not a promise that every home faces the water. If you are considering south of fifth, start by deciding how you want to live: a full-service high-rise, a smaller condominium, or a house. The right fit depends on your daily routine, your tolerance for building costs, and how much the water, dining, and the rest of Miami Beach matter to you.
Talk through a South of Fifth search
What Does South of Fifth Include?
South of Fifth sits where Miami Beach narrows toward Government Cut. The Atlantic is to the east, Biscayne Bay is to the west, and the neighborhood cannot simply sprawl outward. That fixed footprint is why buyers feel the difference from one block to the next. A home near South Pointe Park is not the same purchase as a home a few streets north, even when both listings use the same neighborhood name.
The appeal is real. You get a waterfront setting, restaurants, a park at the tip, and a short trip into the rest of Miami Beach. None of that means every unit has a view, every errand is a walk, or every building offers the same service. Treat the label as the start of a search. Then study the address, the line, and the floor.
If you want a wider map of nearby areas before you narrow to this pocket, read the Miami Beach neighborhood guide. It covers how the rest of the beach compares. This page stays on the southern tip only.
Which Property Type Fits a South of Fifth Plan?
Start with the trade-offs you will actually live with. A larger amenity package often means higher recurring fees. A smaller building can feel quieter, with fewer shared facilities. A house can offer more privacy, and it also puts maintenance on you. None of these is automatically better. Match the property to how you use a home.
| Option. | Who it may fit. | What to verify. |
|---|---|---|
| Full-service condominium. | Buyers who want staff, shared amenities, and a lock-and-leave setup. | Monthly fees, what they cover, rental rules, reserves, and planned work. |
| Smaller condominium. | Buyers who prefer a quieter building and fewer shared spaces. | Services included, how decisions are made, and the building's financial position. |
| Single-family home. | Buyers who want a private residence and direct control of the property. | Condition, insurance, flood exposure, upkeep, and any renovation limits. |
Use the table as a set of questions, not as a ranking. Confirm the fee schedule, the rules, the condition, and the obligations for the specific home. A striking lobby does not tell you whether the budget fits.
How Should You Compare Streets Inside SoFi?
Map your routine before you fall for a listing photo. Walk from the property to the beach, the park, a grocery stop, and the route you would actually drive. A short distance on a map can feel different at the hour you travel, or in the weather you will meet.
- Street setting. Visit more than once. Note traffic, deliveries, noise, and what the block feels like in the evening.
- Exposure. Ocean, bay, Government Cut, and a city outlook read differently here. Ask which way the windows face and what sits directly outside.
- Access. Check parking, guest parking, elevator routes, and how deliveries reach the door. Space is tight in a small grid.
- Light and privacy. A higher floor is not always quieter. Balconies, neighboring towers, and street activity all change the feel of a line.
Compare homes by size, condition, view, floor, and what is included. Neighborhood reputation alone will not explain the price gap between two listings on the same street.
Buyers who also want a waterfront high-rise elsewhere on the beach can use the Miami Beach waterfront condo guide as a separate comparison. It is a product guide, not a substitute for walking this neighborhood. If a mainland high-rise is still in the mix, the Brickell buyer guide shows a different urban pattern, with a different commute and a different street life.
What Should You Review Before an Offer?
For a condominium, ask for the governing documents and the current financials early. Read the budget, reserve funding, recent minutes, insurance summary, rental rules, and any planned or proposed work. Do not treat a polished amenity deck as proof that the building's obligations match your risk tolerance.
Florida's condominium statute is the legal starting point for how associations are governed. Review the current text of Florida Statutes Chapter 718, then ask a Florida real estate attorney how it applies to this purchase. Rules, building facts, and deadlines change. This guide is not legal, tax, or insurance advice.
A practical companion is the Miami luxury condo due diligence guide. Use it for the document checklist. Keep the neighborhood decision on this page. For any home, confirm title, what conveys, insurance availability, and permitted work. The purchase price is only one number in the decision.
How Do You Prepare a South of Fifth Search?
- Rank what you will not give up. Separate a must-have, such as a certain outlook or a lock-and-leave plan, from a preference you could trade.
- Build a full budget. Include association charges or house upkeep, insurance, taxes, and a cushion. Do not stop at the offer price.
- Compare real alternatives. Put two or three homes on one sheet. Note layout, condition, outlook, and rules side by side.
- Tour with a purpose. Visit at a time that matches your schedule. See the garage, the lobby path, and the shared areas, not only the living room.
- Line up the review. Decide which documents and which professionals you need before a deadline starts the clock.
A simple decision sheet keeps a view from crowding out a cost. Write confirmed facts in one column and open questions in another. If a number is unknown, leave it unknown. Do not write zero.
How Should You Compare Two Shortlisted Homes?
Once you have a short list, stop relying on memory. Use the same criteria for every home. Record the asking price, recurring costs, condition, layout, orientation, parking, storage, and the documents you have actually received.
Mark each line as confirmed, still open, or not applicable. An attractive lobby is something you can see. A planned project or a leasing rule usually lives in the documents. If a cost is not confirmed, it stays open. Treating a blank as zero hides the risk.
For condos, compare more than the monthly charge. Ask what the fee covers and what it does not. Note the budget, reserves, insurance, minutes, and any work the association has already approved. A lower fee can still mean a higher total cost if services differ or a project is coming. A higher fee deserves the same document check, not an automatic no.
For houses, shift the sheet to the property itself. Ask which systems have been inspected, which past work has paperwork, and which repairs are soon versus optional. A home that looks ready on a short visit still needs a proper inspection. Specialists should review anything a general inspection does not cover.
Citywide condo shopping has its own questions. The Miami condo buyer guide is the place for that broader pass. Come back here when the choice is specifically this southern tip of Miami Beach.
What Does Daily Life Look Like at One Address?
Neighborhood write-ups flatten differences that you will feel every week. The route from the door to the park, the position of the line, the building entrance, and the street itself all shape the day. Take a test walk at a time that looks like your real schedule. If you plan to be outside often, notice shade, wind, and how far the useful stops actually are.
Think through ordinary logistics. Where does a guest park? How do packages get upstairs? Is the path from the garage reasonable with groceries? What is the process for visitors, contractors, and a move-in? If you travel, ask how keys, access, and routine upkeep work while you are away. When a building rule matters, get it in writing.
Walkability is personal. One buyer wants a short walk to a specific restaurant. Another needs a reliable drive to work or to family. Map your own destinations and check them at the hours you would use them. Close on a map is not the same as convenient.
How Should You Think About Ownership Costs?
Price tags are a poor way to compare these homes. Depending on the property, plan for association charges or house maintenance, insurance, property taxes, utilities, repairs, financing costs, and any work you want to do after closing. Amounts vary by address and by buyer. Get current figures for the property, not a neighborhood average.
On a condo, ask which services the fee includes. Ask whether any project is approved or proposed, and whether an assessment is in place or under discussion. Check the answers against the records. A conversation in a lobby is not a substitute for the budget and the minutes.
On a house, ask about the roof, the exterior, and the mechanical systems in light of the home's age and any past work. An inspection helps. It does not promise that every future repair has been found. Keep room in the budget for what you cannot see yet.
Separate recurring costs from one-time costs. A renovation, a move, furniture, and closing costs all change how much flexibility you have after you buy. Decide what cushion you want to keep. That is how you compare homes on the full ownership picture instead of the asking price alone.
Current listings across the Maya Vander Group's Miami Beach and greater Miami search live on the Florida luxury homes search. Use it to see what is on the market, then judge each South of Fifth option with the checks above.
Questions to Ask Before You Choose
- What does the monthly cost include, and which bills sit outside it?
- Which rules cover leasing, pets, renovations, guests, and shared spaces?
- What work is planned, and which documents support that answer?
- How do this line and this floor change noise, light, outlook, and privacy?
- Which similar sales help explain the asking price?
- Which items need an attorney, an inspector, an insurance broker, or a lender?
Bring a clear picture of how you will use the home. Say whether you expect to live there full time, use it seasonally, or keep a later change open. Name the needs that will not move. A first conversation should tell you what to investigate next. It should not replace legal, lending, inspection, or insurance advice.
Plan your South of Fifth next step
Frequently Asked Questions
Is South of Fifth the same as all of Miami Beach?
No. It is the area south of Fifth Street, at the southern tip of Miami Beach. Other parts of the beach have different streets, building patterns, and daily routes. Compare them only after you know what you need from this pocket.
Are all South of Fifth homes on the water?
No. Waterfront frontage and a water view depend on the address and the line. Confirm the outlook, the sightlines, and any beach or marina access. Do not infer them from the neighborhood name.
Should amenities decide the building?
Amenities matter if you will use them. Also weigh their cost, their condition, the rules, and what they add to the association's obligations. A pool you will not use is still part of the budget.
What is a sensible first step?
Set your priorities and a full budget. Then compare specific homes and their documents. The neighborhood name is the starting point, not the decision.
Decide on the Home, Not the Label
South of Fifth can suit a buyer who wants a Miami Beach address in a small southern setting. The right purchase is still a particular home, with particular costs and rules. Compare real alternatives, verify the documents, and choose around the way you want to live.
Ready to Explore Luxury Real Estate in Miami?
Don't miss opportunities in one of Florida's most desirable markets. Contact Maya Vander today for exclusive access and personalized service.


